Table Of Contents
- Why do governments regulate crypto?
- How is crypto regulated in the United States?
- How does Canada regulate crypto?
- How does the UK regulate crypto?
- How is the EU regulating crypto under MiCA?
- How does China regulate crypto?
- How does Japan regulate crypto?
- How is crypto regulated across South America?
- The bottom line
The Most Recent Crypto Regulations Around the World
What words do we associate with cryptocurrencies? In the public consciousness, you would not be surprised to hear words like volatile, decentralized, risky, innovative, and unregulated. This reflects the journey that this asset class has taken since its inception. Cryptocurrencies have progressed at vastly different speeds across so many markets, and there are a range of good stories, and a fair amount of bad stories, too.
So, crypto regulation is anything but uniform. Unlike traditional financial markets that generally follow harmonized frameworks, the global crypto trading space is still a regulatory patchwork. In some countries, digital assets are embraced as engines of innovation; in others, they’re banned outright. In this article, we will tell you the latest crypto regulations in markets around the world.
Remember, with crypto, the only constant is change. This guide was last updated in October 2026; rules change quickly, so check the relevant regulator's own website before acting.
Why do governments regulate crypto?
Governments regulate crypto because it can challenge the existing financial order built around fiat currencies, central banks, and tightly controlled monetary systems. This is why many policymakers treat digital assets as more than a new technology trend. In practice, regulation is often framed as a way to preserve monetary control and limit disruption to established financial systems.
Fiat money remains the globally accepted standard for trade, taxation, and sovereign economic policy.
Cryptocurrencies, by design, operate outside these centralized frameworks, making it harder for governments to:
monitor capital flows
enforce anti-money laundering (AML) laws
collect taxes
manage economic stability

In this regard, it’s easy to understand why governments are keeping such a close eye on crypto. You will hear all sorts of valid reasons why this is the case:
Unregulated crypto markets can facilitate illicit finance,
They can enable tax evasion,
They can destabilize monetary systems through speculative bubbles, and
They can create vulnerabilities in investor protection and lead to scams.
Ultimately, regulation helps governments reassert control, ensure transparency, and integrate digital assets into the broader financial system without undermining sovereign economic authority.
Governments don’t necessarily oppose innovation.
However, many policymakers, albeit begrudgingly, accept that innovation drives the world forward, and cryptocurrencies are doing exactly that by moving finance into decentralized, real-time networks that anyone with Wi-Fi can access.
It’s messy, chaotic, and yes, wildly volatile, but so was every great invention before it changed the world. If history teaches us anything, it’s that progress doesn’t wait for permission.
So, that said, where do the major economies currently stand when it comes to crypto regulation?
Based on our review of recent policy updates across major crypto markets in 2024 and 2025, the common regulatory themes are remarkably consistent: AML compliance, consumer protection, stablecoin oversight, and clearer tax reporting.
How is crypto regulated in the United States?
With Donald Trump in the White House for a second time, crypto regulation in the US could shift quickly because he strongly favors deregulation.
Critics have raised conflict-of-interest concerns about the president's and his family's crypto ventures, but the industry is far bigger than any single person, however influential.
The US has seen a fragmented and often contentious regulatory landscape. A "regulation by enforcement" approach, primarily led by the Securities and Exchange Commission (SEC), characterized much of the period from 2021 to 2024, leading to a lack of clear federal guidelines.
Lawmakers have struggled to pass comprehensive legislation, while states have also taken varied stances. Recent political shifts, including statements from the Trump administration, suggest a more innovation-friendly approach, though clarity is still limited.
Current Standing & Legislation:
Regulatory Agencies:
SEC: Under former Chair Gary Gensler (appointed by President Biden), the SEC treated many crypto tokens as "securities" under the Howey Test and pursued numerous enforcement actions against crypto companies for unregistered offerings, exchanges, and lending platforms. His stance was broadly seen as cautious and enforcement-heavy.
Donald Trump began his second term as President and ensured there would be significant changes in the leadership and priorities of the SEC. Paul Atkins was confirmed as Chair in 2025, and the SEC has since been more permissive of cryptocurrency activities by:
Prioritizing formal rulemaking over "regulation by enforcement"
Focusing on clear guidelines for crypto issuance, custody, and trading
Reversing restrictive policies like SAB 121 and withdrawing stifling proposed rules
Promoting innovation through "innovation exemptions" and adapting legacy rules
Prioritizing formal rulemaking over "regulation by enforcement"
Focusing on clear guidelines for crypto issuance, custody, and trading
Reversing restrictive policies like SAB 121 and withdrawing stifling proposed rules
Promoting innovation through "innovation exemptions" and adapting legacy rules
Commodity Futures Trading Commission (CFTC): This body views Bitcoin and Ethereum (and potentially others) as "commodities" and regulates derivatives based on them. It advocates for its expanded role in regulating the spot crypto market.
Financial Crimes Enforcement Network (FinCEN): Focuses on Anti-Money Laundering (AML) and Counter-Terrorist Financing (CFT) for virtual asset service providers (VASP), requiring registrations as Money Services Businesses (MSB).
Office of the Comptroller of the Currency (OCC), Federal Reserve and Federal Deposit Insurance Corporation (FDIC): Have recently rescinded prior cautionary joint statements regarding banks engaging with digital assets in spring 2025; the Fed, for example, announced on 24 April 2025 that banks no longer need to notify it in advance of crypto activities. This is a major shift, giving banks more freedom to operate in crypto, such as through custody services, and to serve crypto businesses if they maintain proper risk management.
This aims to open doors for traditional financial institutions.
Key Legislation in Place (or its interpretation):
No single comprehensive federal crypto law.
Existing securities laws (e.g., Securities Act of 1933, Securities Exchange Act of 1934) are applied to crypto assets.
Bank Secrecy Act (BSA) under FinCEN.
State-level "BitLicense" in New York and other state-specific regulations for money transmitters.
Suggested Legislation:
Stablecoin law: The GENIUS Act, the first federal framework for payment stablecoins, was signed into law on 18 July 2025, according to the White House. Regulators are now writing the detailed rules that put it into practice.
Market structure bills: Various proposals, such as the Lummis-Gillibrand bill and FIT21, aim to clarify SEC and CFTC jurisdiction, define digital asset types, and establish consumer protection frameworks. The latest of these, the CLARITY Act, passed the House of Representatives on 17 July 2025 by 294 votes to 134 (House Clerk), but had not been enacted as of October 2026. Why is this important? Because it will allow clear regulatory ownership to be placed under defined agency control.
Administration's Stance: The second Trump administration wants to make the US the "crypto capital of the world" through pro-crypto legislation, and set up a Strategic Bitcoin Reserve by executive order on 6 March 2025 (White House).
The Fed’s (Central Bank) Stance:
It has previously expressed concerns about financial stability risks, consumer protection, and illicit finance associated with crypto.
Acknowledges the potential for innovation but maintains a cautious approach regarding mainstream adoption of unbacked crypto assets.
A January 2025 executive order bars federal agencies from taking any action to establish, issue or promote a central bank digital currency (CBDC), so a US "digital dollar" is off the table for now. The withdrawal of prior crypto directives for banks suggests a more pragmatic, though still risk-aware, engagement with digital assets. In practice, one of the biggest issues in the US market is not the absence of regulators, but the overlap between them, which can leave exchanges, token issuers, and custody providers navigating several compliance interpretations at once.
How does Canada regulate crypto?
Canada has generally adopted a more pragmatic approach than the US, focusing on regulating crypto as financial instruments and service providers.
The emphasis has been on investor protection, AML/CFT, and market integrity, largely through existing securities and money service business frameworks. There has often been a clear push to integrate crypto into the traditional financial system rather than an outright ban.
Current Standing & Legislation:
Securities regulators (CSA, OSC): The Canadian Securities Administrators (CSA), in coordination with provincial regulators like the Ontario Securities Commission (OSC), have clarified that many crypto assets, especially those involving an investment contract, fall under securities law.
National Instrument 31-103 (NI 31-103): Crypto asset trading platforms (CTP) are generally required to register as investment dealers and comply with securities regulations, including know-your-client (KYC) and custody requirements.
Financial Transactions and Reports Analysis Centre of Canada (FINTRAC): This body regulates Money Services Businesses (MSB), which include virtual asset dealers and exchanges, for AML/CFT purposes.
Office of the Superintendent of Financial Institutions (OSFI): It has issued guidelines for federally regulated financial institutions (FRFI) on capital and liquidity treatment of crypto-asset exposures, setting limits on exposure (e.g., typically not higher than 1% of Net Tier 1 capital for Group 2 crypto-assets).
Legislation in Place: Application of existing securities laws, AML/CFT laws, and OSFI guidelines.
Suggested Legislation:
Tax reporting: Canada is committed to adopting the OECD's Crypto-Asset Reporting Framework (CARF) by 2027, with implementation proposed for 2026, increasing tax transparency and reporting requirements for crypto service providers.
Central Bank (Bank of Canada) Stance:
It monitors crypto asset markets for potential systemic risks but currently views them as not posing a significant threat to Canada's financial system due to limited interconnectedness with traditional finance.
That said, the central bank acknowledges the investment interest in Bitcoin but notes its limited use for payments.
After completing its research on a digital Canadian dollar, the Bank of Canada says it has scaled down its work on a retail Central Bank Digital Currency (CBDC) and shifted its focus to broader payments system research and policy.
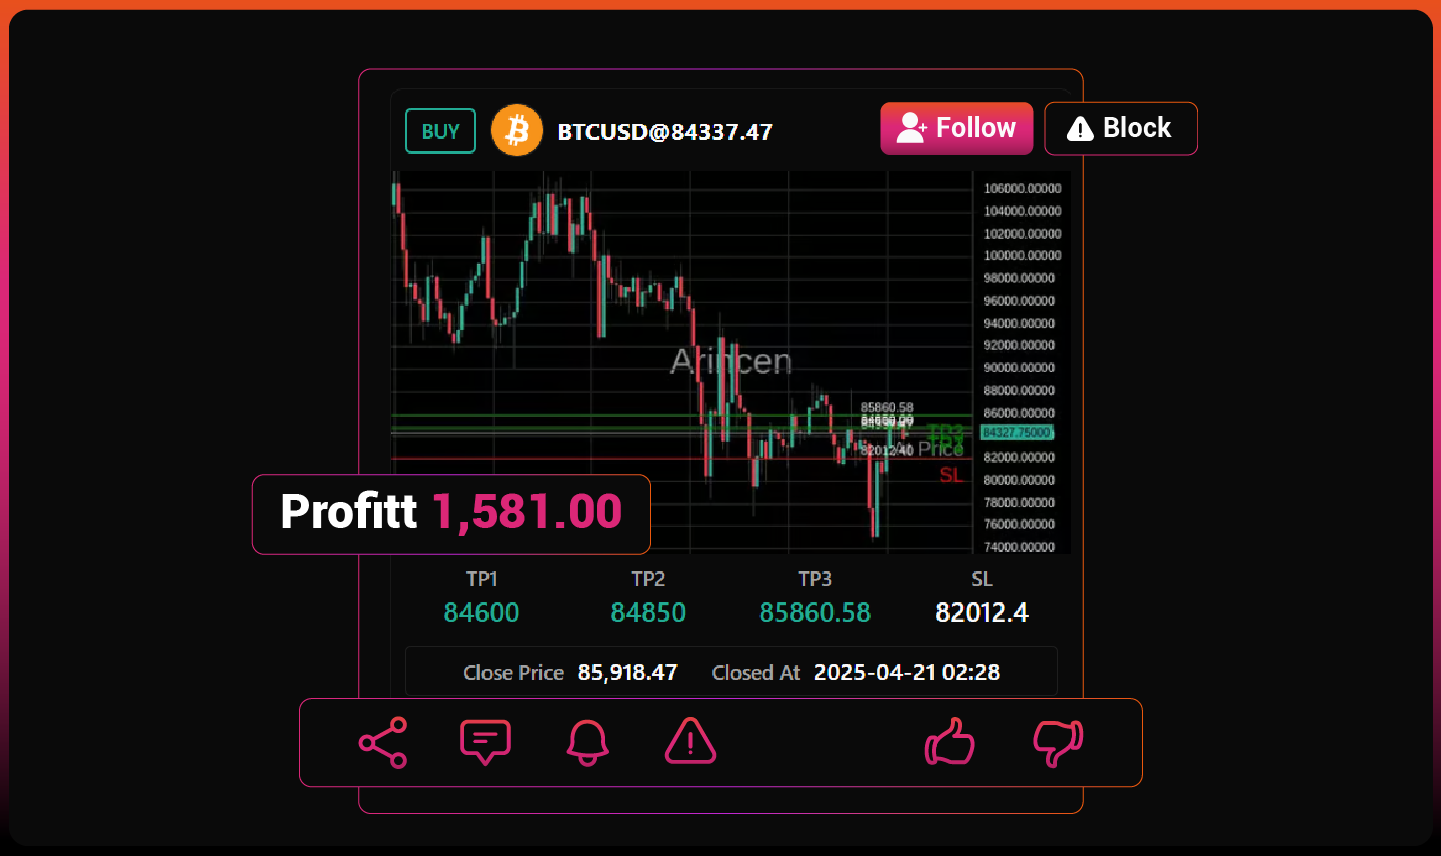
Trade with Real-Time Expert Signals
Follow live signals from experienced traders.
Get entry price, TP levels, SL, and closure updates.
Receive instant alerts when targets or stops are hit.
Track performance with clear, transparent stats.
Stay aligned with the market in real time.
How does the UK regulate crypto?
The UK has aimed for a "technology-neutral" approach, intending to regulate crypto based on its function rather than its underlying technology.
While initially slower than the EU, the UK has been actively developing a comprehensive regulatory framework, particularly for stablecoins and broader crypto activities, emphasizing innovation while mitigating risks.
Current Standing & Legislation:
Financial Conduct Authority (FCA): The primary regulator for crypto in the UK has focused on consumer protection, financial promotions, and AML/CFT. Firms involved in crypto activities often need to register with the FCA for AML purposes.
HM Treasury: Has been leading the policy development for the future regulatory regime.
Financial Services and Markets Act (FSMA) 2000 (Amendments): Draft legislation was published in April 2025, and the final law, the Financial Services and Markets Act 2000 (Cryptoassets) Regulations 2026, was made on 4 February 2026 (FCA). It brings a wider range of cryptoasset activities within the regulatory remit. This includes:
Defining "qualifying cryptoassets" and "qualifying stablecoins" as specified investments
Classifying activities like operating a cryptoasset trading platform, dealing in cryptoassets as principal, and safeguarding cryptoassets as regulated activities, requiring FCA authorization
Applying the Financial Promotion Order (FPO) to cryptoasset promotions
Amending Money Laundering Regulations (MLR)
Stablecoin Regulation: The UK proposes a specific regime for fiat-referenced stablecoins, including one-to-one reserve backing and FCA authorization for issuers. These are a key focus for implementation soon.
Digital Securities Sandbox (DSS): Launched in September 2024 by the FCA and Bank of England to enable firms to test digital asset technology in financial markets under a "test" regulatory regime.
Legislation in Place: Until the new regime starts, primarily existing AML/CFT regulations (Money Laundering Regulations 2017) and financial promotion rules.
Suggested Legislation:
The FCA published its final rules and guidance on 30 June 2026, and the new cryptoasset regime is expected to come into force on 25 October 2027, according to the FCA. Further consultations are expected (e.g., on stablecoin issuance and crypto custody).
Central Bank (Bank of England) Stance:
It works closely with HM Treasury and FCA on the regulatory framework, particularly for systemic stablecoins.
Welcomes proposals for stablecoin regimes, seeing potential for efficiency in payments. For systemic stablecoins, the Bank of England will publish complementary consultation papers.
Actively exploring the possibility of a digital pound (CBDC), currently in the research and design phase, but no decision on issuance has been made. Views it as a potential complement to cash, not a replacement, for future payments.
How is the EU regulating crypto under MiCA?
The EU has become a frontrunner in comprehensive crypto regulation, resulting in the landmark Markets in Crypto-Assets (MiCA) regulation.
The purpose of this proactive approach is to create a harmonized legal framework across all 27 EU member states, providing legal certainty for businesses and investors.
From a comparative research perspective, MiCA is one of the clearest examples of a single-region rulebook replacing fragmented national approaches, which is why many firms now treat the EU as a regulatory reference point when planning market entry.
Current Standing & Legislation:
MiCA (Markets in Crypto-Assets) Regulation: This is the cornerstone.
■ Status: Entered into force in June 2023 and has applied in full since 30 December 2024. Firms already operating under national rules could continue only until 1 July 2026 at the latest while seeking a MiCA licence (ESMA).
■ Scope: Covers the issuance, marketing, and trading of crypto-assets (excluding NFTs, though this is under review) and related services.
Key Provisions:
Authorization for CASPs: Crypto-asset service providers (CASP) must be authorized by national competent authorities (NCA) and meet stringent requirements (e.g., capital, governance, consumer protection, conflict-of-interest management).
Stablecoin Regulation: Specific rules for "asset-referenced tokens" (ART) and "e-money tokens" (EMT), requiring issuers to be authorized and maintain reserves.
Market Abuse: There are strong provisions to prevent insider trading and market manipulation in crypto.
Whitepapers: Regulators have introduced requirements for issuers of crypto assets to publish whitepapers with clear and fair information.
Passporting: Once authorized in one EU member state, CASPs can "passport" their services across the entire EU.
Transfer of Funds Regulation (TFR): Requires crypto service providers to collect and share information on senders and recipients of crypto transfers, aligning with FATF "travel rule" recommendations.
Digital Operational Resilience Act (DORA): Enhances cybersecurity and operational resilience requirements for financial entities, including crypto firms.
Legislation in Place: MiCA is the primary comprehensive regulation. TFR and DORA also apply.
Suggested Legislation:
While MiCA is largely in place, the European Securities and Markets Authority (ESMA) and the European Banking Authority (EBA) are continually developing Regulatory Technical Standards (RTS) and Implementing Technical Standards (ITS) to operationalize MiCA, refining specific aspects. Potential future legislative reviews might address areas like DeFi or NFTs in greater detail.
Central Bank (European Central Bank - ECB) Stance:
So, the ECB views cryptocurrencies as risky, volatile, and not suitable as a reliable store of value or means of payment due to their inherent instability.
It raises concerns about financial stability risks, particularly with growing interconnectedness between crypto and traditional finance, and a lack of visibility into non-bank financial institutions' crypto activities.
It is actively exploring the development of a digital euro (CBDC), seeing it as a way to safeguard strategic autonomy, monetary sovereignty, and enhance the payment system for EU businesses and individuals, rather than relying on private stablecoins or foreign digital currencies.
How does China regulate crypto?
China has pursued one of the world's most aggressive and comprehensive crackdowns on cryptocurrency activities. Starting with restrictions on exchanges and ICOs, it escalated to an effective blanket ban on crypto mining and trading, citing financial stability risks, energy consumption concerns, and illicit activities.
This approach is a major contrast to its parallel push for blockchain technology development and a central bank digital currency.
Current Standing & Legislation:
Outright Ban:
People's Bank of China (PBOC) and other regulators (September 2021): Issued a joint notice (Notice No. 237) declaring all cryptocurrency-related transactions illegal, including trading, order matching, token issuance, and derivatives.
Mining Ban: Significant crackdown on crypto mining operations, forcing most miners to relocate out of mainland China.
Overseas Platforms: Providing online crypto services to Chinese residents by overseas platforms is also considered illegal.
Exemptions: China has generally not banned blockchain technology itself, recognizing its potential for various applications outside of speculative crypto trading.
Hong Kong: Notably, Hong Kong operates under a separate regulatory regime. It has been actively establishing itself as a crypto hub, with a licensing regime for virtual asset trading platforms (VASP) launched in June 2023, allowing licensed exchanges to offer retail trading services. This creates a significant contrast with mainland China.
Legislation in Place: Regulatory notices and directives from various government bodies; legal framework for prohibiting crypto activities.
Suggested Legislation:
While a ban is in place, the primary "mooted" development is the continued expansion and official launch of China's CBDC. Hong Kong has gone further: its licensing regime for issuers of fiat-referenced stablecoins took effect on 1 August 2025 under the Stablecoins Ordinance, according to the Hong Kong Monetary Authority.
Central Bank (People's Bank of China - PBOC) Stance:
It is also actively developing and piloting the digital yuan (e-CNY), its own Central Bank Digital Currency (CBDC).
This is a strategic priority aimed at:
modernizing the payment system
enhancing financial inclusion
potentially challenging the dominance of traditional payment networks and foreign currencies
The PBOC's focus is on a centrally controlled digital currency.
How does Japan regulate crypto?
Japan was an early mover in crypto regulation, particularly after the Mt. Gox hack. Its approach has focused on regulating crypto exchanges and assets as financial instruments, emphasizing consumer protection, AML/CFT, and fostering innovation within a regulated environment. It has often been seen as one of the more crypto-friendly major economies.
Current Standing & Legislation:
Payment Services Act (PSA): This act was amended to define cryptocurrencies as "crypto-assets" and require crypto exchanges to be registered with the Financial Services Agency (FSA). It imposes strict requirements on exchanges, including segregation of client assets and robust AML/CFT measures.
Financial Instruments and Exchange Act (FIEA): Applies to crypto assets that resemble securities ("security tokens"), bringing them under the scope of existing securities regulations.
New Stablecoin Law (Effective June 2023): Recognized stablecoins as digital money, requiring them to be linked to the yen or other fiat currencies and guaranteeing redemption at face value. Only licensed banks, trust companies, and registered money transfer agents can issue stablecoins. This is a significant step toward clear stablecoin regulation.
Recent Legislative Action (Post-DMM Bitcoin Hack - May 2024): The hack at DMM Bitcoin put exchange custody and security, including at the outside firms that exchanges rely on, at the centre of Japan's regulatory agenda.
Legislation in Place: Amended PSA, FIEA, and the new Stablecoin Law.
Suggested Legislation:
Tax Reform: The ruling Liberal Democratic Party's Web3 Project Team has proposed classifying crypto-assets as a distinct asset class under FIEA and shifting tax treatment from miscellaneous income (high progressive rates) to a flat 20% separate financial income taxation, with loss carry-forward provisions. This signals a desire to make Japan more attractive for crypto businesses.
Central Bank (Bank of Japan - BOJ) Stance:
Monitors crypto developments closely, acknowledging their potential impact on financial stability.
Has been actively engaged in experiments and research regarding a Central Bank Digital Currency (CBDC) - "Digital Yen." The BOJ's cautious approach emphasizes extensive public and private sector engagement.
While not directly regulating crypto, the BOJ's monetary policy decisions (e.g., quantitative easing/tightening) can indirectly influence capital flows into risk assets like crypto.
How is crypto regulated across South America?
South America has a highly diverse crypto regulatory landscape, driven by:
economic conditions
inflation rates
political priorities
While some nations have embraced crypto due to economic instability or for financial inclusion, others have taken a more cautious or even prohibitive stance.
However, the region remains a hotbed for crypto adoption, particularly for:
payments
an inflation hedge
Current Standing & Legislation (Focus on major economies):
Brazil:
Approach: Progressive and relatively clear. It recognizes crypto assets as a legitimate investment class.
Legislation (Law 14.478/2022): Came into effect in June 2023. Establishes a legal framework for crypto-asset services, defining them as "virtual assets" and requiring Virtual Asset Service Providers (VASP) to be licensed by the Central Bank of Brazil (BCB) or the Brazilian Securities Commission (CVM), depending on the asset's classification. Focuses on AML/CFT and consumer protection.
Mooted: Ongoing discussions about specific regulations for stablecoins and clearer definitions within the existing law.
Argentina:
Approach: High crypto adoption due to persistent inflation and capital controls. The regulatory approach has been evolving, although sometimes contradictory.
Current Standing: No comprehensive crypto-specific law. Crypto assets are generally treated as intangible assets for tax purposes. The central bank (BCRA) has issued some restrictions.
Legislation: Application of existing tax laws.
Central Bank Ban (May 2023): The Central Bank of Argentina prohibited financial institutions from offering crypto-related services to customers, citing risks to financial stability and consumer protection.
Mooted: Various legislative proposals have been mooted to regulate crypto assets, often with a focus on investor protection and AML/CFT, but none have passed comprehensively.
Colombia:
Approach: Adopting an innovative approach, including regulatory sandboxes.
Current Standing: No specific crypto law, but the financial regulator, Superintendencia Financiera de Colombia (SFC) has launched a regulatory sandbox program (La Arenera) to allow controlled testing of crypto-related business models.
Legislation: Crypto exchanges operate under existing financial regulations, primarily concerning AML/CFT.
Mooted: Development of a comprehensive crypto regulation is anticipated, informed by the sandbox experiments.
Chile:
Developing a regulatory framework that integrates fintech and crypto.
Current Standing: The Financial Market Commission (CMF) supervises financial institutions, and crypto exchanges are subject to AML regulations.
Fintech Law (Passed 2023): This law includes provisions for crypto assets and service providers, aiming to regulate a broad spectrum of fintech activities, including those involving digital assets.
Mooted: Further secondary regulations and specific guidelines under the Fintech Law are expected.
El Salvador: (We’re giving you a brief mention for context, as it's an outlier)
Approach: Bitcoin became legal tender in September 2021. As part of an IMF loan programme approved in February 2025, the law was changed so that private businesses no longer have to accept bitcoin and taxes are paid in US dollars (IMF).
Legislation: Bitcoin Law (2021), amended in January 2025.
Central Bank: The Central Bank of El Salvador (BCR) supervises traditional financial institutions, but the country's unique Bitcoin adoption creates a distinct financial landscape. The IMF has repeatedly advised caution against its legal-tender status.
Central Banks' Stance
They are generally cautious, citing volatility, consumer protection, and financial stability risks.
Many are actively researching and exploring Central Bank Digital Currencies (CBDC) as a safer alternative to private crypto, aiming to:
enhance financial inclusion
reduce costs
strengthen payment systems
Brazil's Central Bank (BCB): Has been piloting a digital-real platform (Drex), focused on tokenization and wholesale uses.
Argentina's Central Bank (BCRA): Has taken a prohibitory stance on banks offering crypto services due to financial risks, while the country grapples with high crypto adoption.
The IMF has noted the potential benefits of CBDCs in LAC for financial inclusion and payment system resilience, while advising caution on unbacked crypto assets.
The bottom line
The latest crypto regulations around the world show one thing clearly: there is no single global rulebook for digital assets. Some governments are encouraging innovation with structured frameworks, while others are tightening restrictions to manage risk, protect consumers, and preserve financial stability.
From the EU’s MiCA framework to stricter policies in China and evolving oversight in the U.S., the direction is clear: regulation is accelerating. For traders, investors, and builders, the smartest move is to stay informed, stay compliant, and stay agile, because the rules of crypto are changing as fast as the market itself.
FAQ
Why is crypto regulation so inconsistent around the world?
Countries treat crypto differently because they prioritize different things, including innovation, tax collection, investor protection, capital controls, and financial stability. Since there is no single global rulebook, regulation remains fragmented and changes quickly.
Which regions are the most crypto-friendly right now?
The EU, Japan, and Brazil stand out for offering clearer frameworks than many other markets. They still regulate heavily, but the rules are more defined, which gives businesses and investors more certainty.
What is MiCA and why is it important?
MiCA is the EU’s crypto rulebook covering issuers and service providers across member states. It matters because it creates shared standards for licensing, disclosures, stablecoins, and consumer safeguards across the bloc.
What is the U.S. approach to crypto regulation today?
The U.S. still has a split system, with the SEC, CFTC, FinCEN, banking regulators and the states all playing roles. Policy became more pro-crypto in 2025: the GENIUS Act (signed 18 July 2025) created the first federal framework for payment stablecoins, but a broader market-structure law such as the CLARITY Act had not been enacted as of October 2026.
Has Canada banned any cryptocurrencies?
No. Canada regulates crypto through existing securities and AML laws. It focuses on investor protection and transparency, requiring platforms to register and comply with financial standards.
Why did China ban crypto while developing its own digital currency?
China views private crypto as a risk to monetary control, financial stability, and enforcement. Its digital yuan serves a different goal: modernizing payments through a state-controlled system rather than allowing decentralized alternatives.
Will crypto become more regulated in the near future?
Yes. Most major markets are moving toward more detailed rules for exchanges, stablecoins, custody, tax reporting, and anti-money laundering. The debate now is less about whether to regulate crypto, and more about how.
What role do central banks play in crypto regulation?
Central banks usually do not write all crypto rules themselves, but they shape policy through warnings, banking guidance, and CBDC research. Their focus is usually financial stability, payments, and limiting systemic risk.
Are there any global rules for crypto regulation?
Not a single universal framework. Instead, countries borrow from international standards on anti-money laundering and transfer reporting, while still writing their own laws on licensing, securities treatment, taxation, and consumer protection.
What countries are most restrictive on crypto?
China is one of the clearest examples, with broad bans on trading, mining, and related services. Other countries may partially restrict crypto, but the level of enforcement and scope of restrictions varies widely.
Which country has the clearest crypto regulation today?
The EU is often seen as the clearest major jurisdiction because MiCA provides a unified framework across member states. Japan also stands out for its structured approach, especially on exchanges, custody, and stablecoins.
Related Articles
 Crypto
6 Best Crypto Leverage Trading Strategies
Trading with leverage is a double-edged sword. However, if you use it wisely, you can boost your profits. Read our article to learn more about the top crypto trading leverage strategies.
 Crypto
7 Common High-Profile Crypto Scams and How to Avoid Them
Fraud has been part of the crypto game since the beginning. Take a look at the most controversial scams out there and how not to fall prey to them.
 Crypto
Best Crypto Exchanges 2026
A crypto exchange is where you can trade your digital currencies. This guide will give you answers on what they are, how they work, and how to choose the best one?
 Crypto
How to Short Crypto? 2026 Full Guide
Shorting is selling crypto at a high price with the intention of buying it back at a lower one. Learn how to short crypto the right way, with tips and risks to consider.
 Crypto
Long Vs. Short Crypto Trading Explained
Long and short are trading positions, suggesting the potential two directions of the price to gain a profit. Learn which and how to use them in crypto trading.